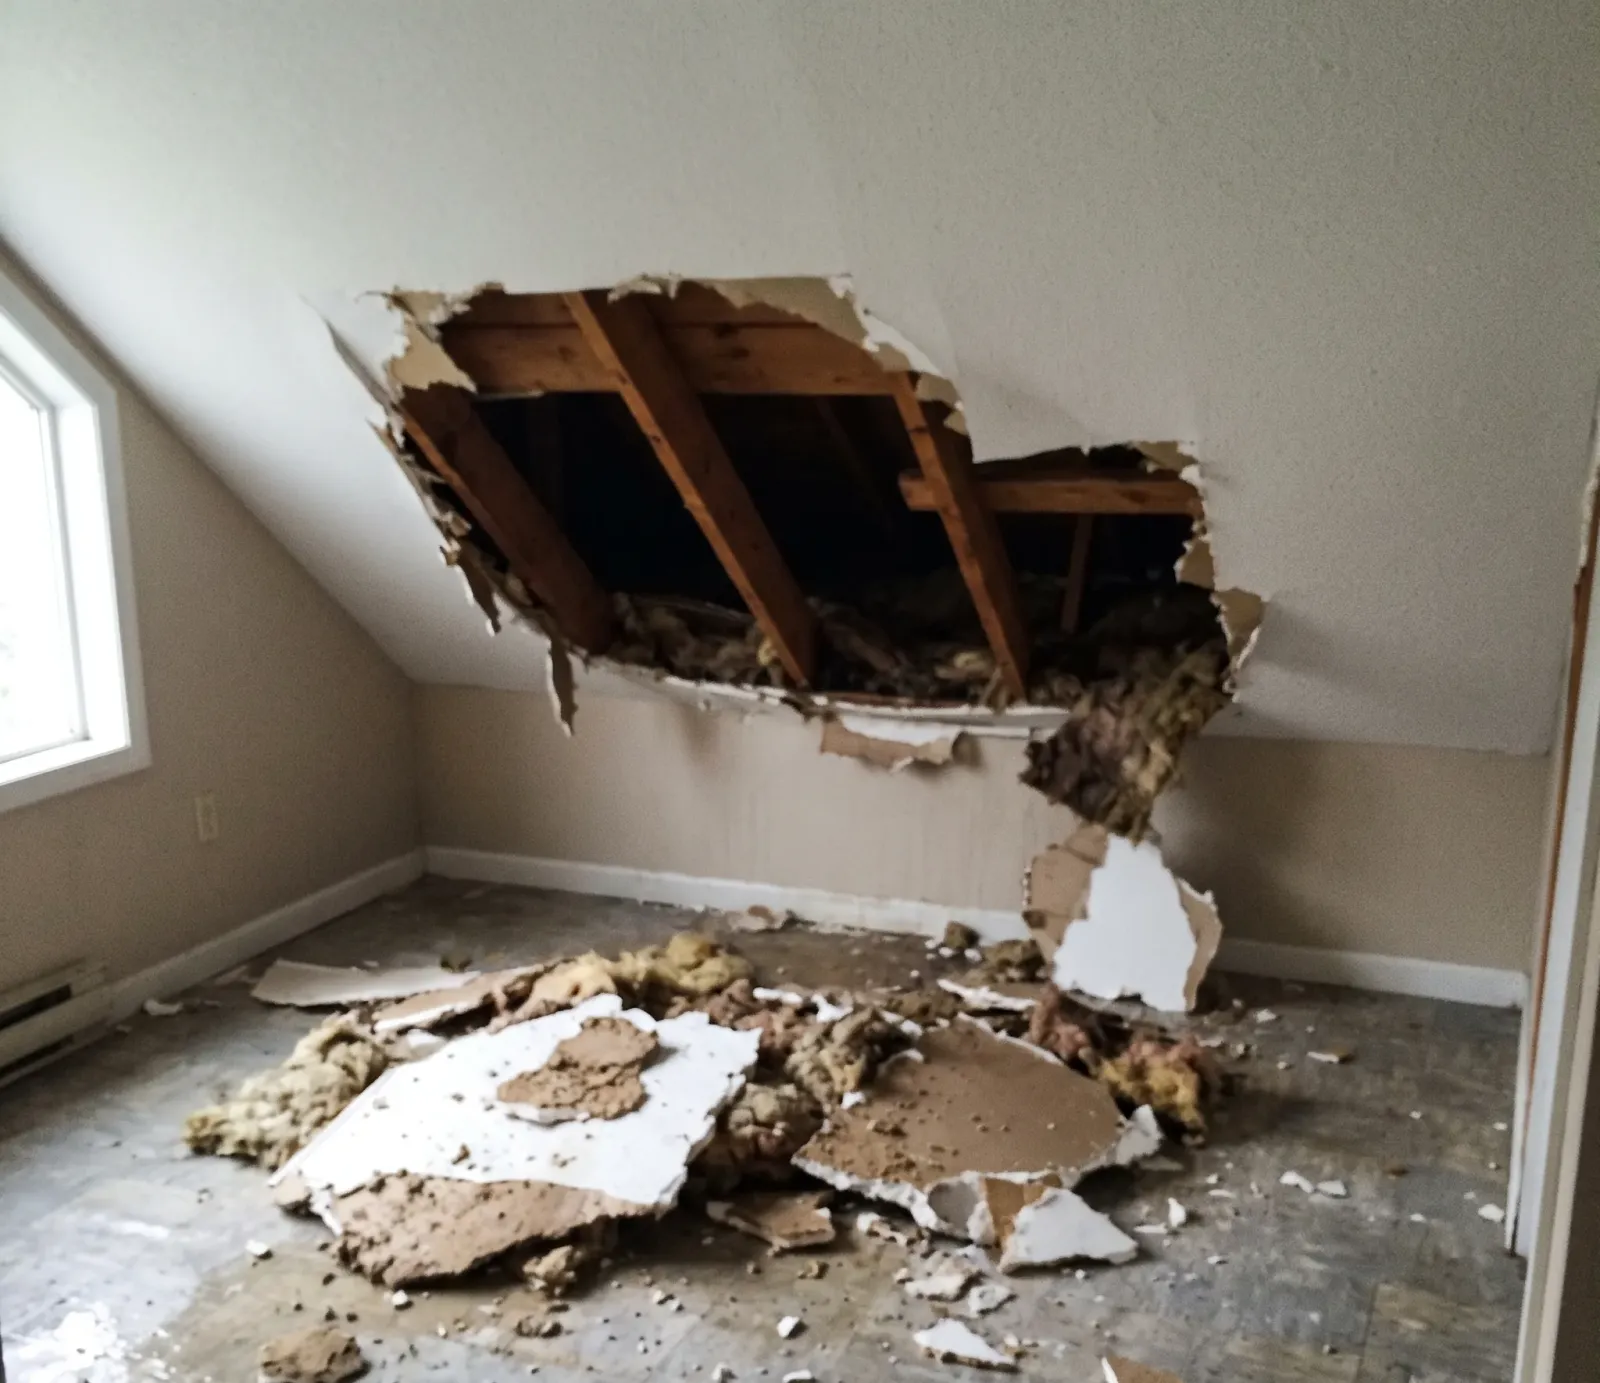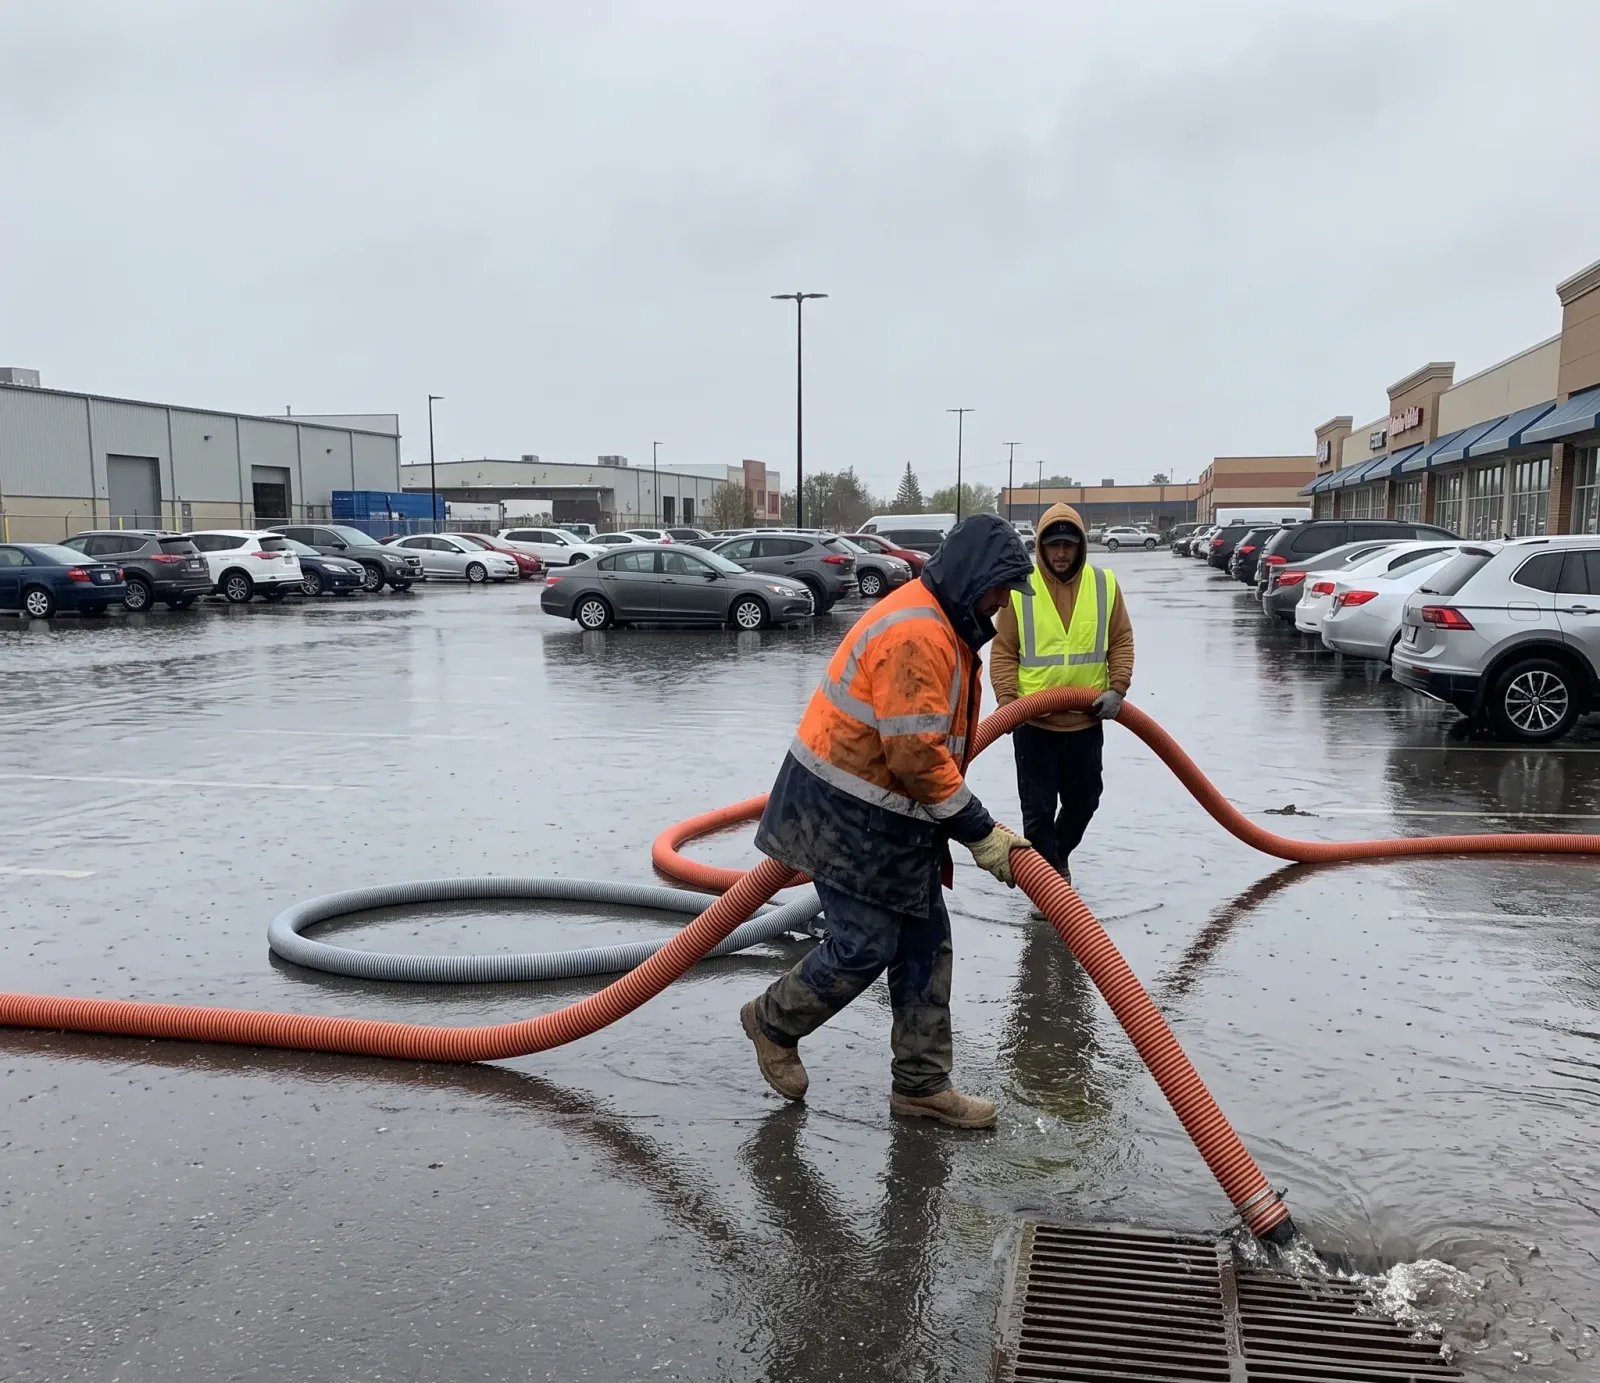
A homeowner in Atlanta calls their insurer after water comes into the house and hears the same word twice: excluded. But two very different events hide behind that word. One is rising surface water finding its way in from outside. The other is sewage or storm runoff pushing back up through a drain or fixture. A standard policy treats them differently, and knowing which one happened, before the adjuster ever shows up, changes what a homeowner can actually claim.
What Surface Water Means
Surface water is rain or runoff that rises outside and finds a way in from ground level: a low door threshold, a window well, a foundation crack near grade. Atlanta's flooding is rainfall-driven, not coastal, so this shows up after a hard storm sends water across a yard or street faster than the ground or storm drains can take it. A basic homeowners policy treats this as the flood exclusion. It does not matter that the water started as rain. Once it is on the ground and moving, it is surface water, and it is excluded.
Why a Named Peril Matters
Homeowners insurance is built around named perils: it lists what is covered and treats everything else as outside the policy. Flood, in the insurance sense, is one of the things a standard policy names as excluded rather than covered. That is true whether the water came from a creek overflowing somewhere in the city or from a storm simply overwhelming a yard's drainage. The exclusion is not about how bad the water was. It is about where the water came from before it reached the house.
Getting Flood Insurance Separately
Because a standard policy excludes flood, covering that risk means buying a second, separate policy, most commonly through the National Flood Insurance Program, or NFIP, or through a private flood carrier offering similar coverage. This is not an add-on to the homeowners policy. It is its own contract, with its own premium, its own deductible, and its own claim process entirely apart from the homeowner's regular insurer. A homeowner anywhere in Atlanta, on a ridge or near a creek, can typically buy this coverage regardless of whether a lender requires it.
What Sewer Backup Means
Georgia homeowners policies follow the same national logic: water that comes down from the sky or up from the ground and reaches a house from outside is treated differently than water that fails from inside it. A pipe bursting under a Virginia-Highland kitchen sink is sudden and accidental. Rain from a storm near Peachtree Creek overtopping its banks and running into a Buckhead crawl space is rising surface water, and a standard policy treats that as flood, excluded outright regardless of how fast or unexpected it was.
The Endorsement That Fixes It
Unlike flood, sewer backup can usually be added back into an existing homeowners policy, not bought as a separate contract. Insurers commonly offer a water backup endorsement, sometimes called a sewer and drain backup endorsement, as an optional add-on for a modest annual amount. It sits on top of the base policy and specifically restores coverage the base policy otherwise excludes. A homeowner who has never asked about this endorsement may simply not have it, even though nothing stopped them from adding it.
Reading the Water's Path
The clearest way a homeowner tells the two apart is to trace where the water first appeared and which direction it was moving. Water pooling against an exterior wall, coming under a door, or rising from a window well points outward, toward surface water and the flood exclusion. Water coming up out of a floor drain, a shower, a toilet, or a basement fixture points backward, through the plumbing, toward sewer or drain backup. The entry point tells most of the story before anyone else gets involved.
When the Two Overlap
A single storm can sometimes cause both at once. A heavy rain overwhelms a yard and also overwhelms the municipal sewer system it drains toward, and a homeowner ends up with surface water at the foundation and backup through a drain in the same event. In that case, each source is judged on its own path into the house. Water that came in from outside falls under the flood exclusion; water that came back up through the plumbing falls under the backup question. One event, two separate coverage questions.
Sudden Loss vs. Slow Seepage
One quick way to sort the two apart: think about where the water came from. If it rose from outside, a swollen creek near Proctor Creek or Peachtree Creek pushing past the yard and in under the door, that is surface water, and a standard Atlanta homeowners policy will not pay for it — only a separate NFIP or private flood policy does. If it came up from inside, out of a toilet, tub, or a low fixture, during heavy rain, that points to sewer or drain backup, which needs its own endorsement. An adjuster will ask exactly this before assigning a policy limit.
Deductibles and Policy Limits
A water backup endorsement carries its own policy limit, separate from the dwelling coverage on the rest of the homeowners policy, and often a separate deductible as well. A flood insurance policy through the NFIP works the same way, with its own limit and deductible independent of the homeowners policy entirely. A homeowner who only checks their main dwelling limit after a loss, without checking whether an endorsement or a separate flood policy even exists, may find there is simply nothing there to check against.
Before Water Ever Comes In
The only way to know which coverage a home actually has is to read the policy, or call the agent, before a storm rather than after one. A homeowner anywhere from Buckhead to East Atlanta can ask two direct questions: does this policy have a water backup or sewer and drain backup endorsement, and is there a separate flood policy in place through the NFIP or a private carrier. Either answer is useful. Finding out there is a coverage gap during a claim is the expensive way to learn it.
Which Exclusion Actually Fits Your Loss
A homeowner near English Avenue or Vine City who has watched a storm push water toward Proctor Creek has reason to ask about flood coverage specifically, since that watershed carries a long, documented history of repeat flooding. Someone in an older Grant Park or Decatur home with aging clay or cast iron lines has a stronger case for a water backup endorsement, since root intrusion and pipe age raise backup risk independent of weather. Either gap gets closed the same way: a call to the current carrier, a look at the declarations page, and a decision before the next storm rather than during one.
Dealing with this in your home?
A basement near Ormewood Park can sit dry for a year, then take on water the first time a real downpour hits. Atlanta's red clay sheds rain rather than soaking it in, so water piles up against a foundation wall fast, especially on lots that slope toward Intrenchment Creek. This post covers what that pattern actually means for a home.